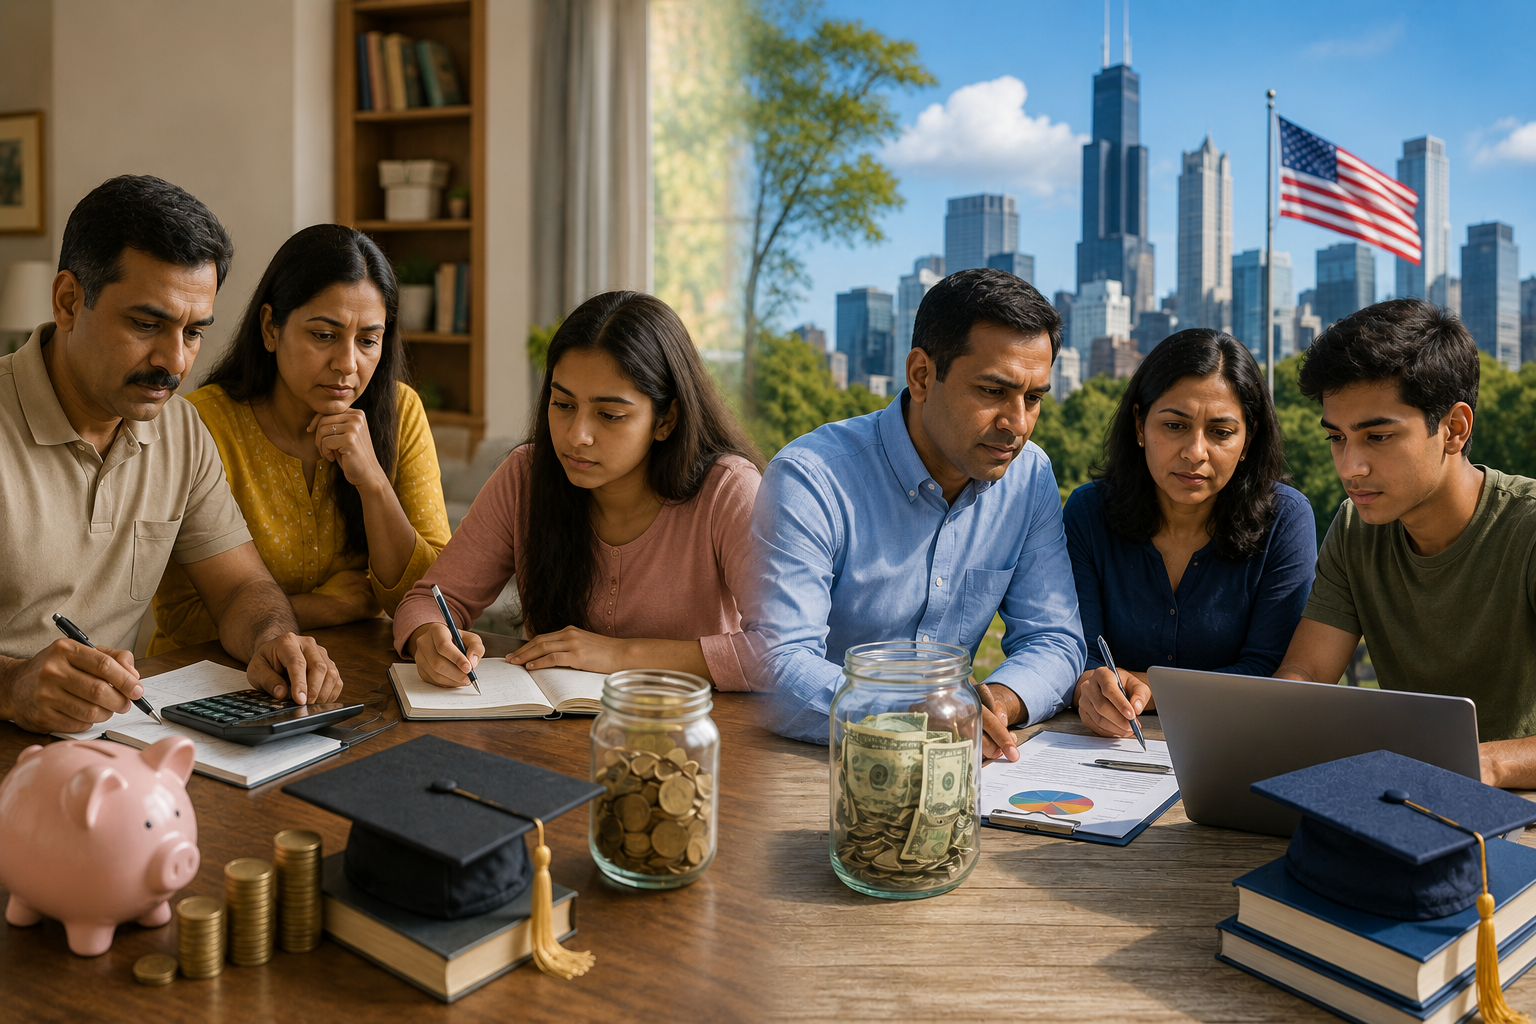
For many families, paying for a child’s higher education has become one of the biggest financial goals after buying a home and planning for retirement.
But the way families prepare for that expense can look very different depending on where they live.
An Indian family may be deciding between a competitive public institution, an expensive private college or an overseas university. A US-based NRI family, meanwhile, may have access to tools such as 529 college-savings plans, scholarships and a more structured college-financing system.
So, who is actually better placed to handle rising education costs—Indian parents or US-based NRIs?
The answer is not simply about income. It also depends on when families start saving, where the child studies, access to financial-aid programmes and how much of the education cost is funded through savings versus loans.
The cost of education is no longer just about tuition
When parents calculate the cost of higher education, tuition is usually the first number they consider.
But the actual bill can include accommodation, food, books, transportation, technology, insurance, travel and other personal expenses.
This becomes particularly important when a student moves to another city or another country.
In the US, for example, the College Board estimates that the average annual student budget for 2025–26 ranges from $21,320 at public two-year colleges to $65,470 at private nonprofit four-year institutions. The average budget for an in-state student at a public four-year institution is $30,990, while an out-of-state student faces an average budget of $50,920.
That means families cannot realistically plan for college by looking at tuition alone.
Indian parents face a different challenge
In India, access to highly reputed public institutions can be extremely competitive.
For families that do not secure one of the limited seats at such institutions, private colleges can become an alternative, often involving significantly higher fees.
Some Indian parents also decide to send their children overseas, where the total cost can rise dramatically because tuition is combined with accommodation, living expenses and currency fluctuations.
Recent reporting highlights how Indian families increasingly have to treat education as a long-term financial commitment rather than an expense that can simply be handled when admission arrives. (The Economic Times)
This is why starting the financial planning process early can make a major difference.
Why starting early matters
Suppose parents know that their child will need a large education fund 10 or 15 years from now.
They have two broad choices.
They can gradually build the money over many years, or they can wait until the admission date approaches and then arrange a large amount through savings, investments or loans.
The first approach generally gives families more flexibility.
Starting early allows investments to potentially compound over a longer period. It also means parents can spread contributions across many years instead of trying to produce a huge amount of money within a short period.
A recent financial-planning discussion in India illustrates this challenge: education costs can rise considerably over long periods, making an early investment strategy particularly important for families targeting a large future corpus.
US-based NRIs have an additional planning tool
One of the biggest advantages available to many US-based families is the 529 college-savings plan.
A 529 plan is designed specifically for qualified education expenses and can provide tax advantages when used according to applicable rules.
This gives families a dedicated mechanism for building education savings over time.
US families can also combine savings with scholarships, grants, income and other sources of funding.
The latest US college-financing data shows that families typically use a combination of resources rather than relying on one source alone.
This doesn’t mean every NRI family is financially comfortable. US college costs can be extremely high, particularly at private universities.
But the availability of dedicated savings and financial-aid mechanisms can make long-term planning more structured.
Scholarships can change the equation
Another important difference is the role of scholarships and financial aid.
In the US, the published price of a college is not necessarily the amount every student ultimately pays.
The College Board reports that the majority of full-time undergraduate students receive some form of grant aid, meaning the net price can be substantially different from the advertised price.
Indian families also have access to scholarships and financial assistance, but the opportunities vary considerably by institution, course, academic performance and family circumstances.
For parents in either country, researching scholarships before admission—not after receiving the college offer—can be an important part of financial planning.
Indian parents often rely more heavily on loans
Education loans can be useful when families have insufficient savings.
For an Indian family sending a child abroad, however, the size of the required loan can become substantial.
A large education loan can create pressure not only during the student’s studies but also after graduation.
This is particularly important when the student’s future income is uncertain.
The question parents should ask is not simply:
“Can we get the loan?”
It should be:
“Can our family comfortably manage the repayment if the student’s career takes longer than expected to take off?”
That distinction can prevent an education decision from becoming a long-term financial burden.
NRIs have advantages—but they also face high costs
It would be wrong to assume that US-based NRIs automatically have an easier time.
The cost of higher education in America can be enormous.
For 2025–26, the average published tuition and fees alone are $11,950 for public four-year in-state colleges and $45,000 for private nonprofit four-year institutions, before considering the rest of the cost of attendance.
Housing and food can add thousands more each year.
An NRI family may therefore earn in dollars but still face a very large education bill.
Their advantage is often the ability to plan within the same currency as the future expense, along with access to US-specific savings and financial-aid mechanisms.
Currency risk is a major issue for Indian families
For Indian parents funding education abroad, currency movements add another layer of uncertainty.
A family may estimate the cost of an overseas degree in rupees today, only to discover that the rupee has weakened significantly by the time tuition payments are due.
For example, if a university charges tuition in US dollars, a weaker rupee means the same dollar amount requires more rupees.
This makes overseas education planning different from saving for a degree at an Indian university.
Parents may need to consider not only education inflation but also exchange-rate risk.
Who is better placed?
There is no universal winner.
Indian parents may have an advantage if:
- They start saving many years before college.
- Their child attends an affordable domestic institution.
- They build a diversified education corpus.
- They avoid excessive dependence on education loans.
- They carefully compare domestic and overseas options.
US-based NRIs may have an advantage if:
- They begin using education-specific savings tools early.
- Their income and savings are in US dollars.
- Their children qualify for scholarships or financial aid.
- They have access to employer benefits or other education resources.
- They plan for the full cost of attendance rather than tuition alone.
Ultimately, early planning can matter more than geography.
The smartest approach is to plan backwards
Instead of asking, “How much should we save every month?”, parents can start with the end goal.
For example:
Step 1: Estimate the likely cost of the degree today.
Step 2: Estimate how many years remain before the child starts college.
Step 3: Account for education inflation.
Step 4: Add accommodation, food, travel and other expenses.
Step 5: Consider scholarships or grants that might reduce the amount.
Step 6: Calculate how much the family can realistically save or invest each month.
Step 7: Keep a separate emergency fund so that education savings aren’t disrupted by unexpected expenses.
This approach creates a target rather than relying on guesswork.
Don’t sacrifice retirement for education
There is another mistake parents can make: putting every available rupee or dollar into their child’s education fund while ignoring retirement.
A child can potentially borrow for education or receive scholarships.
A parent cannot easily borrow money to fund retirement.
That doesn’t mean parents should underfund education. It means the two goals need to be planned together.
A sustainable financial plan should ideally protect retirement savings while gradually building the education corpus.
The bigger lesson
The debate between Indian parents and US-based NRIs isn’t really about who has more money.
It is about who starts earlier, who understands the true cost and who has a better strategy for funding it.
US-based families can benefit from structured college-savings options and financial-aid systems, but American universities can carry extremely high price tags. Indian families may have access to lower-cost domestic education, but limited seats at top public institutions and the growing popularity of overseas education can create significant financial pressure.
For both groups, the most powerful financial tool may be the same: time.
Parents who begin planning years before admission have more opportunities to build savings, adjust their investment strategy, search for scholarships and avoid taking on excessive debt.
The earlier the planning starts, the less likely a child’s college admission is to become a financial emergency.
Disclaimer
This article is for general informational and educational purposes and does not constitute financial, investment, tax or education advice. Education costs, financial-aid rules, tax treatment and investment returns can vary by country and individual circumstances. Families should consult qualified financial and tax professionals before making major education-funding decisions.
Learn more about our site on contactarchive2in.com
Contact us on our email id contactarchive2in@gmail.com
Leave a Reply
You must be logged in to post a comment.